

Archive — Feature first published in the July/August 2021 issue of 3D ADEPT MAG and posted online on September 30, 2021. Transactions, roles and outlooks refer to that period. The tables distinguish funding announcements from proceeds actually received; they do not describe the companies’ current stock-market status.
Understanding how additive manufacturing companies access public markets.
In 2020 and 2021, several additive manufacturing (AM) companies announced plans to access public markets by merging with a Special Purpose Acquisition Company (SPAC). Others chose a conventional Initial Public Offering (IPO), or a listing following a private placement. These funding routes involve different requirements.
- How does a SPAC work?
- Why did some AM companies choose this route?
- What limitations and risks need to be examined?
On August 26, 2020, Desktop Metal announced a business combination with Trine Acquisition Corp., a SPAC backed in part by HPS Investment Partners. HPS participated in the financing; it was not another operating company merging with Desktop Metal. Completion was announced on December 10, 2020.
Other companies in AM and its wider ecosystem subsequently announced similar transactions. The table records announced 2020–2021 terms, not a final account of cash available. Gross proceeds, net proceeds and expected balance-sheet cash are not directly comparable; redemptions and transaction expenses can reduce the funds received.
| Company | SPAC | Announced valuation and basis | Announced financing and scope |
|---|---|---|---|
| Desktop Metal | Trine Acquisition Corp. | USD 2.5bn — equity value | Up to USD 575m gross announced; approximately USD 580m gross reported at the December 2020 closing. |
| Markforged | one | USD 2.1bn — equity value | Up to USD 425m gross: USD 215m in SPAC trust cash and USD 210m PIPE, assuming no redemptions. |
| VELO3D | JAWS Spitfire Acquisition Corp. | USD 1.6bn — enterprise value | Up to USD 500m cash proceeds, including a USD 155m PIPE. |
| Shapeways | Galileo Acquisition Corp. | USD 410m — enterprise value | USD 195m expected net proceeds, already including the USD 75m PIPE; assuming USD 139m in trust and no redemptions. |
| Rocket Lab | Vector Acquisition Corp. | USD 4.1bn — enterprise value | Up to USD 320m in trust and approximately USD 470m PIPE. Expected balance-sheet cash also reflected other sources and uses. |
| Fathom | Altimar Acquisition Corp. II | USD 1.5bn — enterprise value | USD 80m PIPE plus available SPAC trust funds; USD 80m was not the total financing. |
| Bright Machines | SCVX Corp. | USD 1.6bn — equity value | Proposed merger: up to USD 435m gross, including USD 230m in trust and USD 205m PIPE. |
| Redwire | Genesis Park Acquisition Corp. | USD 615m — enterprise value | Approximately USD 170m expected balance-sheet cash, assuming no redemptions; USD 100m committed PIPE. |
| Fast Radius | ECP Environmental Growth Opportunities Corp. | USD 1.4bn — equity value | USD 445m expected gross proceeds: USD 345m in trust plus USD 100m PIPE, assuming no redemptions. |
Other companies accessed public markets without a SPAC merger. The following table distinguishes IPOs, private placements preceding admission and a listing plan discussed at the time. A share price, an ADS price and funds raised measure different things.
| Company | Market or plan | Date or status | Verified financing data | Activity |
|---|---|---|---|---|
| Massivit 3D | Tel Aviv Stock Exchange (TASE) | March 2021 | NIS 169m raised; approximately NIS 490m pre-money and NIS 660m post-money announced valuation. | Large-format 3D printing systems. |
| MeaTech 3D | Nasdaq | March 2021 | USD 10.30 announced price per ADS representing ten ordinary shares; initial offering of approximately USD 25m gross before the option. | Cultivated-meat and bioprinting technologies. |
| Norsk Titanium | Euronext Growth Oslo | May 18, 2021 | Admission following a private placement of approximately USD 38m, according to the listing announcement. | Titanium components made using directed energy deposition. |
| Xometry | Nasdaq Global Select Market | June 30, 2021 expected in the pricing announcement | USD 44 per share; 6,875,000 shares offered, or USD 302.5m gross before option and fees. | On-demand manufacturing marketplace. |
| Freemelt | Nasdaq First North Growth Market | July 7, 2021 | April pre-IPO placement: approximately SEK 85m at SEK 10 per share; funds raised are not the valuation. | Electron-beam powder-bed fusion systems. |
| Rokit Healthcare | Proposed listing in South Korea | Plan discussed for 2021 | No price or amount confirmed in this feature; a listing plan is not a completed IPO. | 3D bioprinting. |
What is a SPAC and how does it work?
“Generally, a SPAC is formed by an experienced management team or a sponsor with nominal invested capital, typically translating into a ~20% interest in the SPAC (commonly known as founder shares). The remaining ~80% interest is held by public shareholders through “units” offered in an IPO of the SPAC’s shares. Each unit consists of a share of common stock and a fraction of a warrant (e.g., ½ or ⅓ of a warrant)”, a PwC report reads.
A SPAC is a company without operating activities formed to raise capital and seek a business combination. The SPAC initially undertakes an IPO; the target subsequently accesses the public market through the business combination, subject to its closing conditions.
The rights attached to founder shares, public shares and warrants depend on the transaction documents. In the structures described by PwC, founders generally elect directors before the business combination; that is not a universal rule for every company after a merger.
For a target, this route can provide financing and sponsor expertise. It does not remove the need to prepare financial statements, governance and the obligations of a public company.
Helen Boyle & William Samengo-Turner, senior associates at law firm Allen & Overy LLP explain: “SPACs offer young and fast-growing tech businesses seeking a listing an alternative to the traditional IPO. Many will not have the credentials of a traditional IPO candidate, possibly being unable to deliver the kind of long-term financial and operating track record traditionally expected of a successful IPO. They may be in the very early stages of development, looking for ways to finance the research and development programmes that their future success depends on, and are certainly likely to be pre-profit and in some cases pre-revenue (unusual on a traditional IPO)”.
Why did some AM companies choose a SPAC?
Analyses published in 2021 described strong interest from many SPACs in growing technology businesses. Several AM companies, in turn, sought capital to fund development. This does not establish a sector-wide preference for SPACs.
Negotiating a valuation with a sponsor and accessing additional investors can influence the decision. A technology’s innovative nature does not, by itself, explain or justify a financing structure.
A potentially shorter timetable can also appeal to a target. The comparison still needs to cover total fees, dilution, funds actually available and the time needed to operate as a public company.
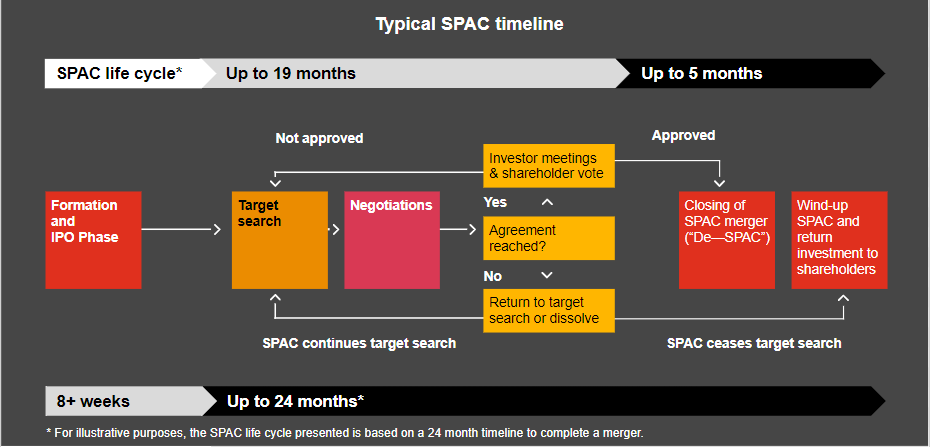
The PwC diagram below illustrates a 24-month lifecycle. This is indicative: the deadline depends on the SPAC’s documents and any approved extensions.
“Following the IPO, proceeds are placed into a trust account and the SPAC typically has 18-24 months to identify and complete a merger with a target company, sometimes referred to as de-SPACing. If the SPAC does not complete a merger within that time frame, the SPAC liquidates and the IPO proceeds are returned to the public shareholders.
Once a target company is identified and a merger is announced, the SPAC’s public shareholders may alternatively vote against the transaction and elect to redeem their shares. If the SPAC requires additional funds to complete a merger, the SPAC may issue debt or issue additional shares, such as a private investment in public equity (PIPE) deal”, they point out. For this reason, “under the rules governing them [see the table below], SPACs must identify firms they can merge with within 24 months after they have raised their funds or they will be wound up and the IPO proceeds returned to investors”, Ivana Naumovska, lecturer at INSEAD, a business school with campuses in France, Abu Dhabi and Singapore notes.
Editorial clarification — Voting on the merger and electing to redeem shares are separate decisions: voting in favour does not necessarily prevent redemption. The SEC discusses this in its review of 2020–2021 transactions. The timings and mechanisms quoted above describe the structures discussed at the time, rather than an immutable rule.
The proposed benefits come with risks. This comparison follows the themes of KPMG’s 2021 analysis; quoted timetables and compensation structures are indicative and need to be assessed transaction by transaction.
| Topic | Potential benefit | Limitation or risk |
|---|---|---|
| Timetable and dilution | Faster execution than an IPO “A SPAC merger usually occurs in 3–6 months on average, while an IPO usually takes 12–18 months.” | Shareholding dilution: “SPAC sponsors usually own a 20 percent stake in the SPAC through founder shares or “promote,” as well as warrants to purchase more shares. SPAC sponsors also benefit from an earnout component, allowing them to receive more shares when the stock price achieves a specified target over a certain timeframe which could lead to further dilution.” |
| Valuation and cash | Valuation negotiated with the SPAC before closing; this guarantees neither proceeds received nor future trading price. | Shareholder redemptions can reduce cash. Additional financing or renegotiation may be required. |
| Financing and readiness | Potential access to SPAC funds and additional investors, subject to conditions. | Compressed timeline for public company readiness: Although the SPAC sponsor may offer help during the merger process, the target company usually takes the brunt of preparing for required financials in the SEC filings and establishing public company functions, such as investor relations and internal controls, under a much shorter deadline than in an IPO. |
| Marketing and diligence | Less marketing resources: “A SPAC merger doesn’t need to generate interest from investors in public exchanges with an extensive roadshow (although raising PIPE involves targeted roadshows).” | The scope of diligence and responsibilities needs examination. A SPAC merger does not remove disclosure obligations or financial diligence. |
| Support | Access to operational expertise: (AM) private companies can benefit from their SPAC sponsors’ experience in finances and management | Placement arrangements and participants differ from a conventional IPO. A different underwriting structure does not mean there are no checks or liabilities. |
Source: KPMG’s 2021 analysis, John Lambert and Sarmed Malik. The three quoted passages in the table are retained from the original article; other cells have been clarified.
A call for caution in mid-2021
When this feature was written in 2021, several transactions carried high announced valuations. A public listing could provide resources to fund growth, but the headline valuation was neither revenue nor available cash.
That enthusiasm also raised questions about the strength of projections and the risk of a market reversal. A promising technology does not guarantee a company’s stock-market performance.
Asked for this feature about AM’s prospects and market risks, Arno Held, then Managing Partner at AM Ventures Management GmbH, offered an encouraging assessment without claiming to predict share prices:
“Our planet and our society are faced with massive challenges. If we want to make the transition to a sustainable civilization, we must adapt our ecologic and economic behavior. Changing our consumption means that products must change which means that production must change. We must avoid waste, increase the lifespan of products and reduce the distances that products have to travel as physical goods. All these challenges are addressed by digital manufacturing in general and Additive Manufacturing technologies very specifically.
On AM Ventures’ tech radar which identified more than 600 AM startups in 2021 alone, we can see that half of the AM companies founded this year are applications companies. This is an entirely new trend since we have started monitoring startup activities more than 7 years ago and means that we have finally learned how to use AM technologies and apply it in order to revolutionize how products are developed, produced and distributed.
Of course, markets are performing in cycles which are sometimes bearish and sometimes bullish. The overall trend, though is very encouraging and we are only just at the beginning of the digital manufacturing age”.
Arno Held’s assessment concerns industrial development. His start-up figures are attributed to AM Ventures and are not an exhaustive market census. Raising capital, through a SPAC or another route, guarantees neither profitability nor the company’s long-term survival.
As per the words of Held, “profitability and success are never granted in business. They are much rather the result of extremely hard work in the right market, at the right point in time, with a sound business model and done by the right team of individuals. Still, all these factors can only increase the likelihood for success but will never give a 100% guarantee.”
Access to public markets broadens financing options; its value needs to be assessed against each company’s business, risks, capital needs and obligations.
First publication: 3D ADEPT MAG, July/August 2021.
Related archive coverage: Desktop Metal announces the Trine transaction; completion in December 2020.
THE 3D ADEPT WEEKLY NEWSLETTER
The industry moves fast. Stay ahead.
Every week, the latest additive manufacturing news, in-depth features and real-world applications, straight to your inbox. Plus, be the first to know when a new issue of 3D ADEPT Mag is out.
Free · One email a week · Unsubscribe anytime
Clicking loads our email provider’s sign-up form, including its analytics and Google’s anti-bot protection. You’re only subscribed if you complete the sign-up. Read our privacy policy.