Feature from the January/February 2024 edition of 3D ADEPT Mag, published online on July 11, 2024. Market data mainly concern 2023; the speakers’ outlook relates to 2024.
Desktop 3D printers, popularized among consumers in the 2010s, also have a place in professional workshops. Filament-extrusion machines have been joined by resin systems serving fields such as jewelry and dentistry. Which needs can they meet alongside industrial systems, and how should growth in this segment be interpreted?
One machine format, several price classes
“Desktop” primarily describes a machine format, not a universal $5,000 price ceiling. Nor does it describe the origins of additive manufacturing: 3D Systems dates commercialization of its SLA-1 to 1987, well before the popularization of personal printers. In the figures discussed here, CONTEXT uses price classes distinct from machine format and end use.
The media attention surrounding personal printers in the 2010s created high expectations. Understanding their industrial role requires distinguishing that consumer visibility from the applications, capabilities and constraints of individual systems.
Eventually, with the increasing focus on industrial 3D printing, desktop 3D printing has been unconsciously relegated to the status of “a consumer or educational technology.” Yet, in the 2023 data analyzed by CONTEXT, “entry-level printers remain the hottest segment” of the market.
Reading the market figures in context
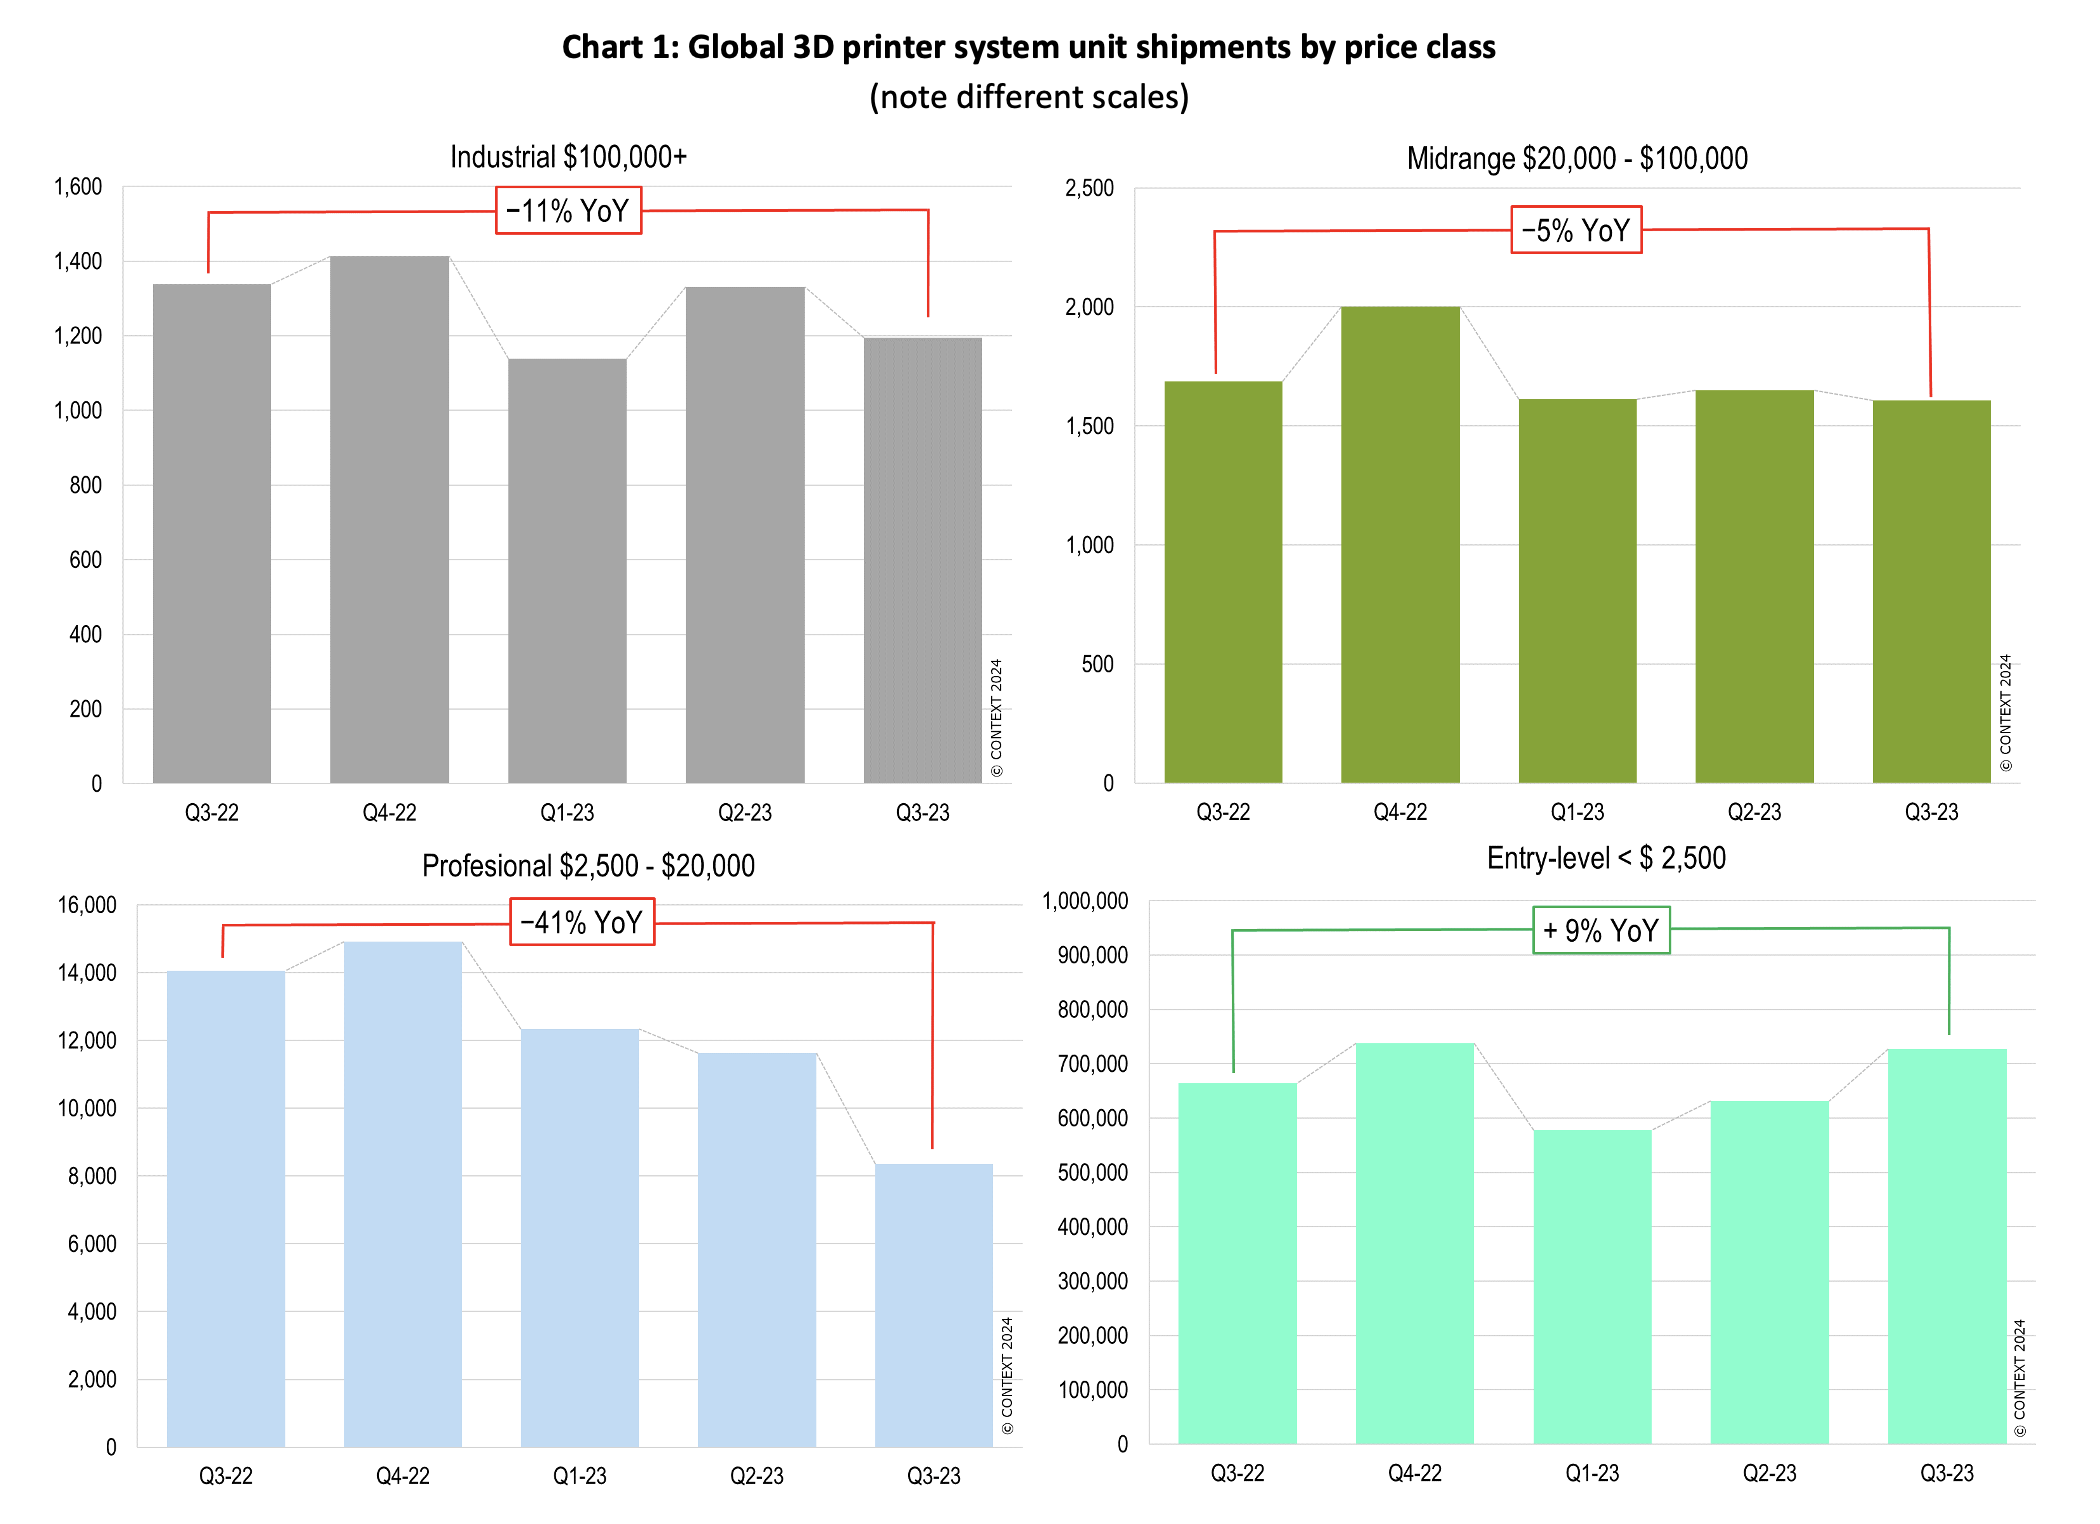
CONTEXT tracks global 3D printer shipments quarterly. Its January 16, 2024 release defines entry-level systems as machines costing less than $2,500. Shipments in this class grew by 9% in Q3 2023 compared with Q3 2022.
Before Chris Connery, then VP of Global Analysis and Research at CONTEXT, explains these results, I would emphasize that “consumer or educational technology” is not a pejorative label. In the figures supplied for this interview, entry-level printers represented 28% of global system revenues over the twelve months from Q4 2022 to Q3 2023. This revenue share is distinct from the number of machines shipped.
“While most of the industry headlines rightly surround happenings in the industrial price class (which accounted for 53% of the global system revenues in the TTM), the low-end 3D Printers are not just toys for consumers with this segment representing an important gateway for many to learn and understand various 3D Printing concepts,” Connery outlines.
Speaking of the reasons why these entry-level printers remain the hottest segment, he continues:
“On a trailing twelve-month’s basis (Q4-22 to Q3-23) compared to a year-ago (Q4-21 to Q3-22) shipment growth was even stronger with +12% more printers shipped globally. While this side of the market continues to see gains by market share, leaders like Creality, Anycubic and Elegoo (with Creality holding a particularly strong market-share lead), upstarts like Bambu Lab have really taken the market by storm and helped to grow this market. While in the past, products at the low end were assumed to be just for consumers, research shows that companies like Bambu Lab have seen strong growth in non-consumer markets.
For this reason, CONTEXT has recently moved away from classifying such products as “PERSONAL” 3D Printers (or “Desktop” or “Consumer”) printers to rename this low-end as “ENTRY-LEVEL” to help highlight the increasing sales of these products in more professional markets. To better highlight this trend, shipments in the price-class CONTEXT calls PROFESSIONAL (which consist of printers in the $ 2,500 to $ 20,000 price-range) have seen a -27% drop on a TTM (trailing-twelve-months) basis showing the cannibalization of PROFESSIONAL products by lower-priced ENTRY-LEVEL printers.
Key to this growth in the ENTRY-LEVEL category (and decline in the PROFESSIONAL category) has been global inflation which has pushed price points up, causing buyers to seek lower-price alternatives. The introduction of more feature-rich “professional” type products at lower prices in this ENTRY-LEVEL category has seemingly been well received and allowed buyers to comfortably shift demand from higher-priced PROFESSIONAL products to lower-priced ENTRY-LEVEL products without feeling that they have sacrificed functionality or quality.”
The comparison periods differ: +9% covers Q3 2023 alone, while +12% and −27% in the quotation refer to trailing twelve-month periods. The −41% decline for professional printers in the chart below is a quarterly year-on-year comparison, not the twelve-month result. The four panels also use different axis scales.
I hear what Connery is explaining about those entry-level 3D printers and I can’t help but think that somehow, these brands that have the strongest market share (Creality, Anycubic and Elegoo) have been victims of their reputation – that is “designed for consumers and makers”. I still remember how a Creality employee told me two years ago that he sold about 200 Creality 3D printers to a big aerospace company but nobody would ever know about that. The fact is, it’s fancier to say that a multinational conglomerate buys 3 industrial 3D printers rather than 200 Creality desktop machines.
The example of about 200 Creality machines is a recollection of a conversation with an employee. The buyer is unnamed and the sale is not independently documented in this feature.
To avoid such generalization and labels related to desktop 3D printing, Connery seems to recommend one should rather categorize those 3D printers by price-classes:
“Often times people reference the “consumer goods” segment as a key end-market for 3D Printing/Additive Manufacturing but indeed it gets a bit confusing when painting the “3D Printing” market as one, cohesive market. For example, there are printers which costs millions of dollars and sit on factory floors, down to desktop variety products which cost a few-hundred dollars and are often used by general consumers typically in the home. To help compartmentalize various solutions and end-markets, CONTEXT compartmentalizes printer hardware by price-classes which it calls ENTRY-LEVEL (for printers under $ 2,500), PROFESSIONAL (those ranging in price from $ 2,500 to $ 20,000), MIDRANGE ($ 20K – $ 100K) and INDUSTRIAL ($ 100K+).
Beyond this high-level price-class distinction, printers can be further segmented by printer type (such as polymer resin-based VAT Photopolymerization printers or polymer Material Extrusion printers or even laser-based metal Powder Bed Fusion printers in the INDUSTRIAL price-class), different materials which various printers can handle (such as Polymers, Metals, Ceramics, Composites, Bio, etc.), end-markets in which these printers are used (such as Aerospace, Medical, Hobby, etc) and even the principle use of these printers (used for prototyping, for single end-part production, for mass-customization, for volume production, etc.) Often when people reference the “consumer goods segment” of the 3D Printing market, they mean the use of industrial machines in the mass production of consumer goods.
Today already, industrial 3D printers are used for manufacturing of certain consumer goods like the mid-soles of running shoes (a consumer good). Others are experimenting with using 3D Printers to mass-produce jewelry or even parts for mobile phones and smartwatches. Another way that people sometimes reference “consumer goods” when talking about 3D Printing, however, is the in-home use of ENTRY-LEVEL printers for general consumers to make products for themselves. For its tracking, CONTEXT classifies the end-markets for ENTRY-LEVEL 3D printer usage either by those unique to the consumer market including: Hobby/DIY, Gadget, Household and Scale Model or by their principal use including: DIY, Toys&Games, Hobby/Household and Fan Art.
The growing trend being seen however is the use of these products for more industrial and professional end-markets including: Automotive, Medical & Healthcare, Dental, Aerospace & Aviation, Jewelry, Education, R&D, Art & Architecture, Energy, Oil & Gas and Movie Props. Some areas for the biggest growth in ENTRY-LEVEL printer shipments have been in Dental (from resin-based printers) and in Automotive, Medical & Healthcare, Aerospace & Aviation and Jewelry markets all of which considered professional (versus consumer).”
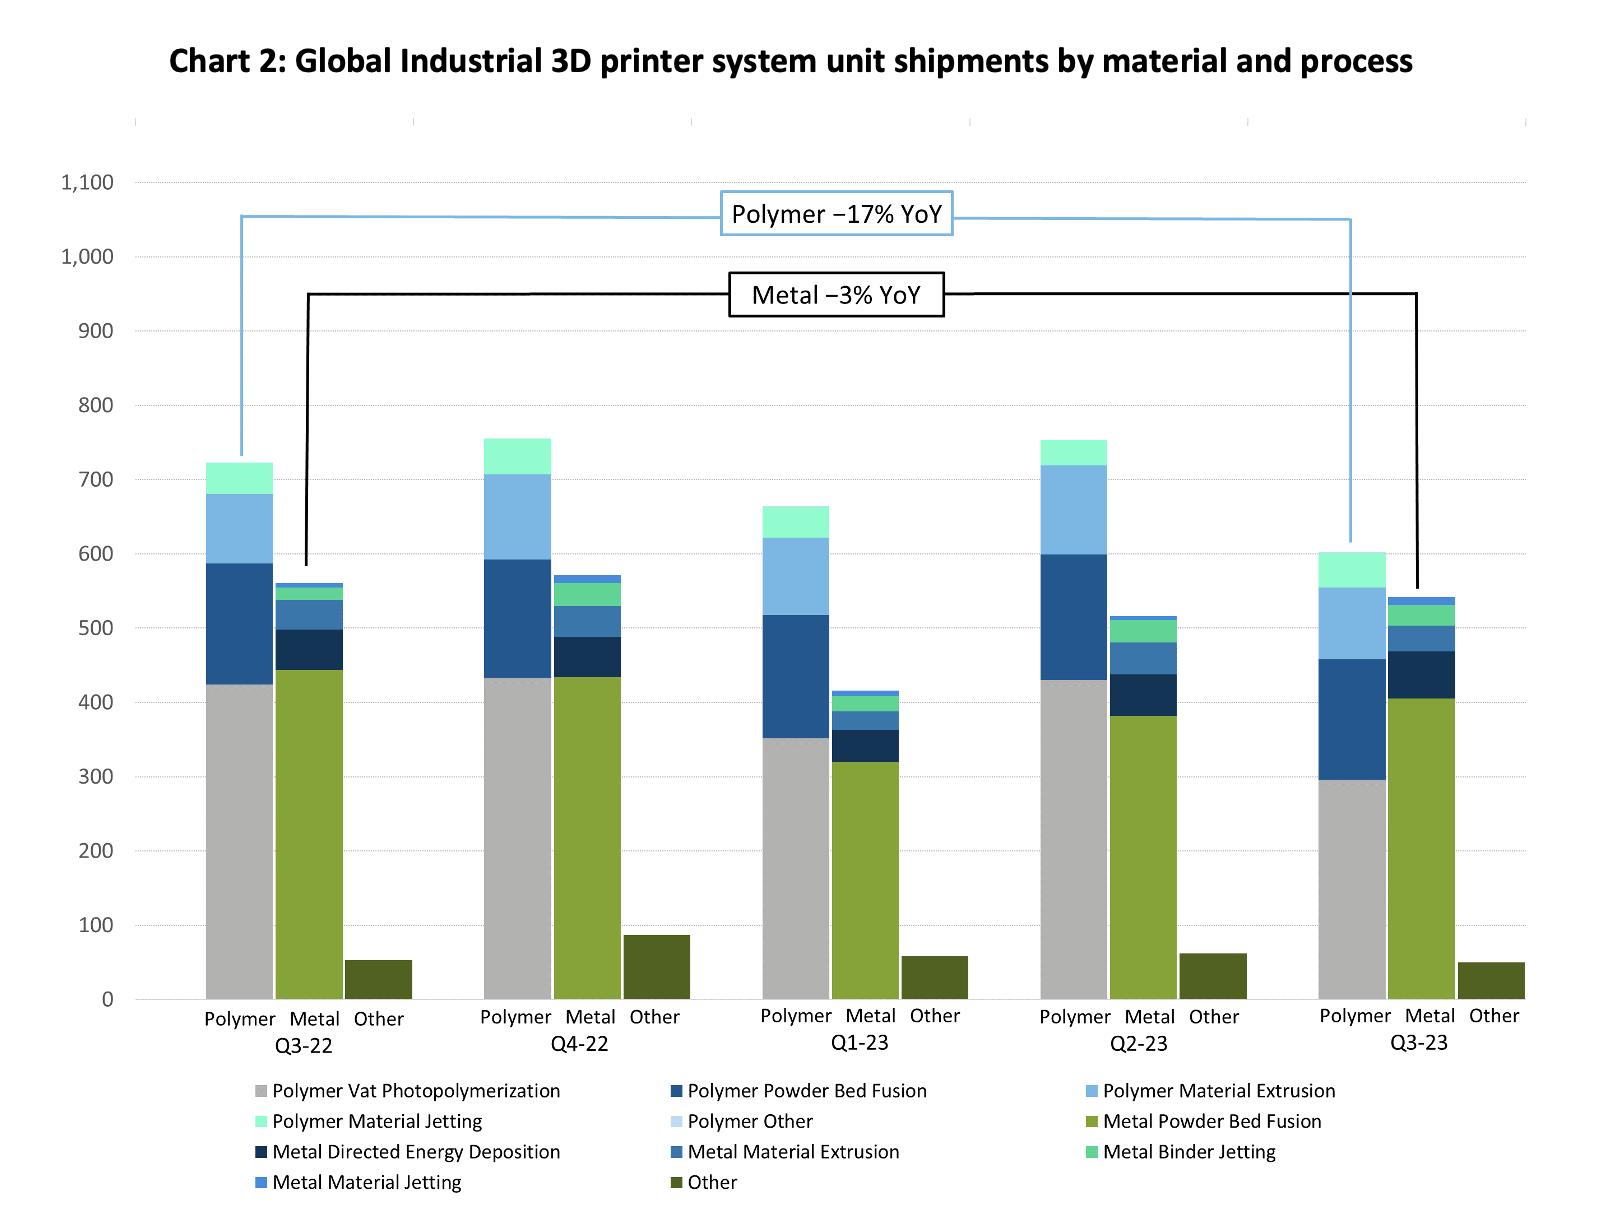
The next chart covers only CONTEXT’s industrial price class, starting at $100,000. It does not measure shipments of all 3D printers or of the desktop segment alone.
Several machines or one industrial system?
Improvements in hardware, software and materials can broaden the applications accessible to desktop machines. They do not make all systems interchangeable: materials, part size, repeatability, qualification, human intervention and production capacity still need comparison for the intended use.
That being said, for Mitch Debora, CEO of Mosaic Manufacturing, a Canada-based 3D printer manufacturer, “the reason businesses are choosing to invest in several professional level printers over a single industrial system is all about scale and cost control. The demand for additive manufacturing is increasing significantly within businesses in product development and manufacturing. They understand that multiple printers running in parallel will significantly outperform a single industrial printer in both throughput and part cost.
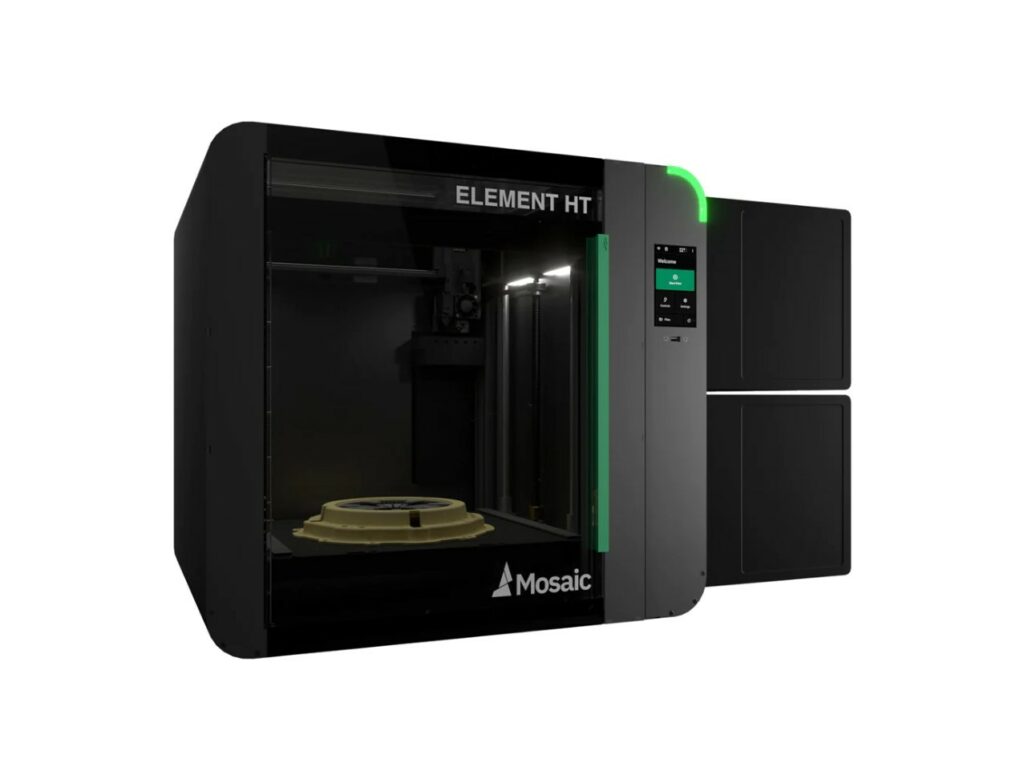
There is a case to be made for $ 100k+ industrial printers in niche applications where a specific feature set is required but for the most part, investing in 5 x $ 10k capable professional printing systems will put a business in a much better position. We see this all the time at Mosaic where businesses will sell off their legacy industrial printers and replace them with several of our ELEMENT HT multi-material and high temperature printers.”
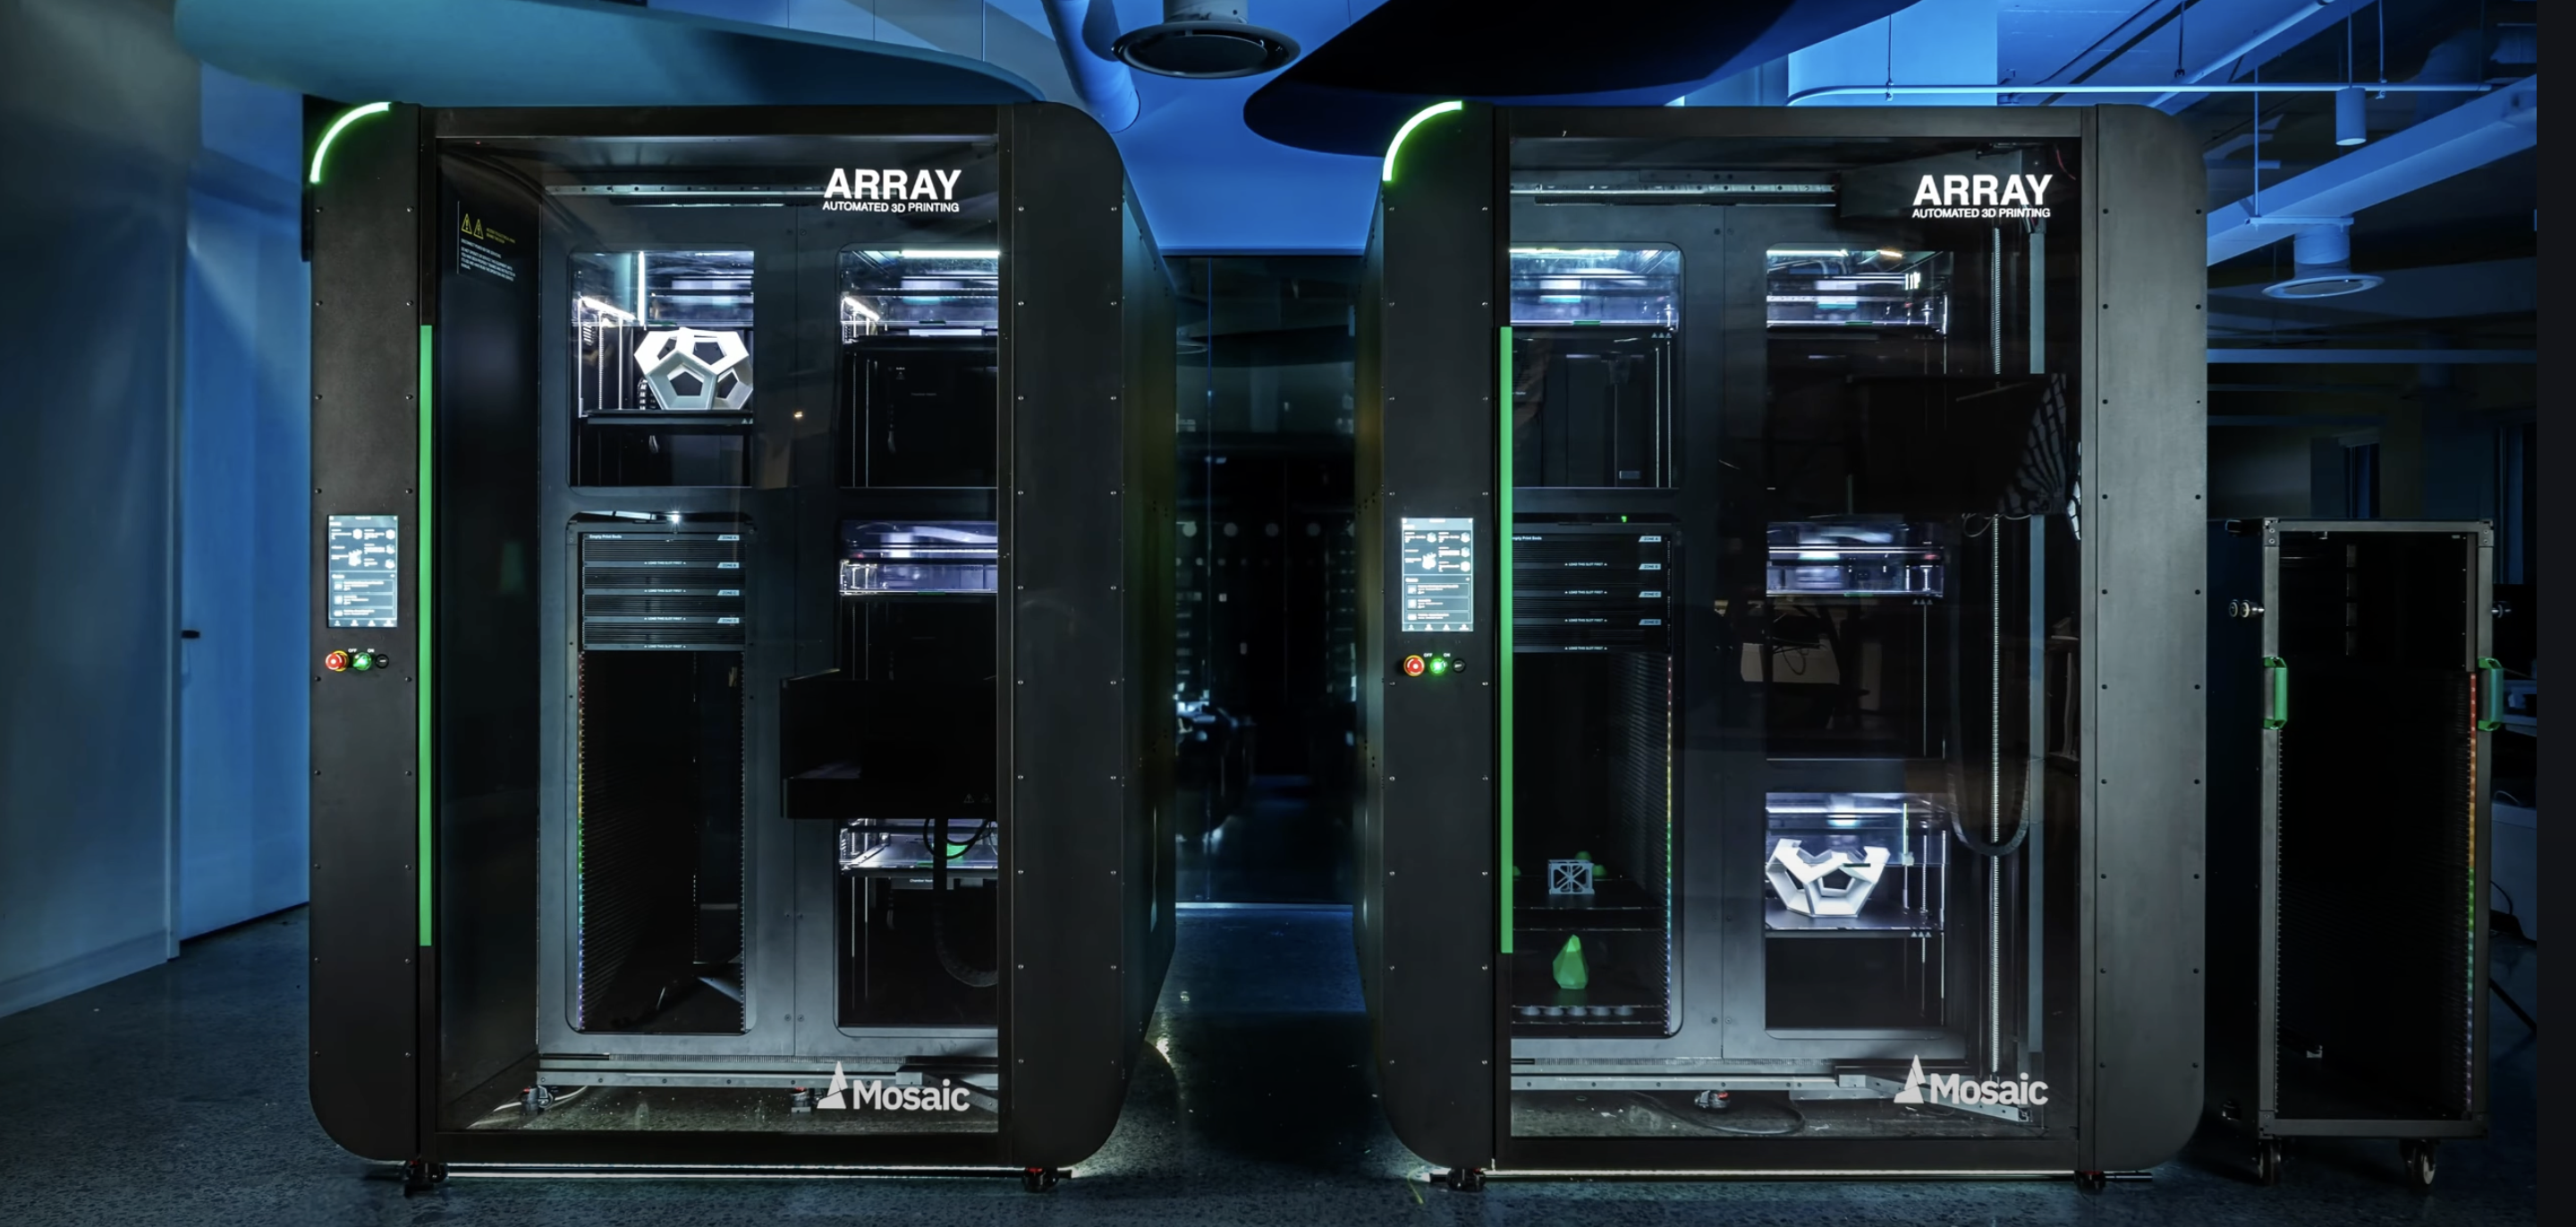
Taking the example of its Element and Array 3D printers, he explains the reasons that may lead one company to invest in the Element solution rather than the Array: “At Mosaic, we offer a desktop printer called Element as well as an automated production system run by robotics called Array. Typically a business that has demand for 5+ printers will purchase an Array since the robotics free’s up their employees time to work on value generating work rather than spending time operating the printers 24/7.
Businesses see a very quick ROI on Array by freeing up the staff’s time thanks to the robotics in Array. Businesses who invest in Element typically do so either because they don’t have the capacity requirements that Array offers or because they are looking to validate a business case before investing in a fleet of Arrays. It is common for us to see a customer buy an Element and then upgrade to an Array or to buy an Array and then to upgrade to 5 Arrays – the modularity of these building blocks makes it effortless for companies to incrementally grow capacity with their business.”
Debora is presenting his company’s business case. The throughput, part-cost and return-on-investment comparisons are his assessments; no detailed comparative study is supplied in this interview. Total fleet cost also needs to include materials, maintenance, labor, post-processing and conforming-part yield. Purchase price alone cannot establish the result.
The outlook expressed for 2024
I am more optimistic about desktop 3D printing and how it can be deployed across industries to achieve various manufacturing purposes. Bear with me, I am not saying desktop 3D printers could match the performance of industrial machines. Industrial 3D printers will always lead the way in some industrial settings, but there is a legitimate place today for desktop 3D printing in such settings as well.
“I don’t see it as a rise and fall of desktop printers so much as I see it as the rise of desktop printers alongside the rise of industrial printing systems,” Mosaic Mfg CEO reacts when asked if it was a “rise and fall” situation.
“At times it can seem like the desktop segment is falling but I think this is an illusion and is more a symptom of industrial systems outpacing desktop systems at that moment. Both segments are growing at a healthy pace year over year and are complementary. For example, it is common that industrial applications are inspired by teams who had access to desktop printers (at home or at work) and connected the dots between challenges in their business and the capabilities of additive manufacturing. The more capable and accessible that hobby grade desktop systems at the low end of the market become, the larger the funnel of technical people there will be who will inspire the next 100 killer applications for additive manufacturing. This year I expect desktop printers to become more capable in material properties, throughput, and user experience,” he concludes.
This dossier was first published in the January/February 2024 edition of 3D ADEPT Mag. Featured image: Desktop 3D printer Element HT. Credit: Mosaic Mfg
Review note: the entry-level threshold has been corrected in the French version. Desktop format, technological origins and statistical periods have been clarified. The apparent transcription error “ride” has been corrected to “rise”; the speakers’ historical assessments remain attributed.
THE 3D ADEPT WEEKLY NEWSLETTER
The industry moves fast. Stay ahead.
Every week, the latest additive manufacturing news, in-depth features and real-world applications, straight to your inbox. Plus, be the first to know when a new issue of 3D ADEPT Mag is out.
Free · One email a week · Unsubscribe anytime
Clicking loads our email provider’s sign-up form, including its analytics and Google’s anti-bot protection. You’re only subscribed if you complete the sign-up. Read our privacy policy.