

April 2, 2025, a day he called “Liberation Day”, Trump declared a national emergency regarding the national trade deficit and announced “reciprocal tariffs” on all countries not subject to other sanctions.
Obviously, a lot of countries and companies were affected around the world. The impact of tariffs is multifaceted and perceived differently depending on a company’s position in the AM ecosystem.
Our recent conversation with Stratasys CEO gives a tangible example of how the company has adjusted after the implementation of these measures by relocating filament production from Israel to the USA. Certainly, part of this adjustment is also the recent opening of its Americas Regional Corporate Headquarters (ARCH), in June 2026.
The new 200,000-square-foot facility in Minnetonka, Minnesota, underscores the company’s continued commitment to the U.S. market and to strengthening the high-tech manufacturing capacity.
But every company is not Stratasys. How have other companies adjusted? Does it advantage US-based businesses? How about those based outside of the USA, yet providing their services to the country of Uncle Sam? This dossier aims to provide clarity on that.
First, the good and the bad of tariffs for AM
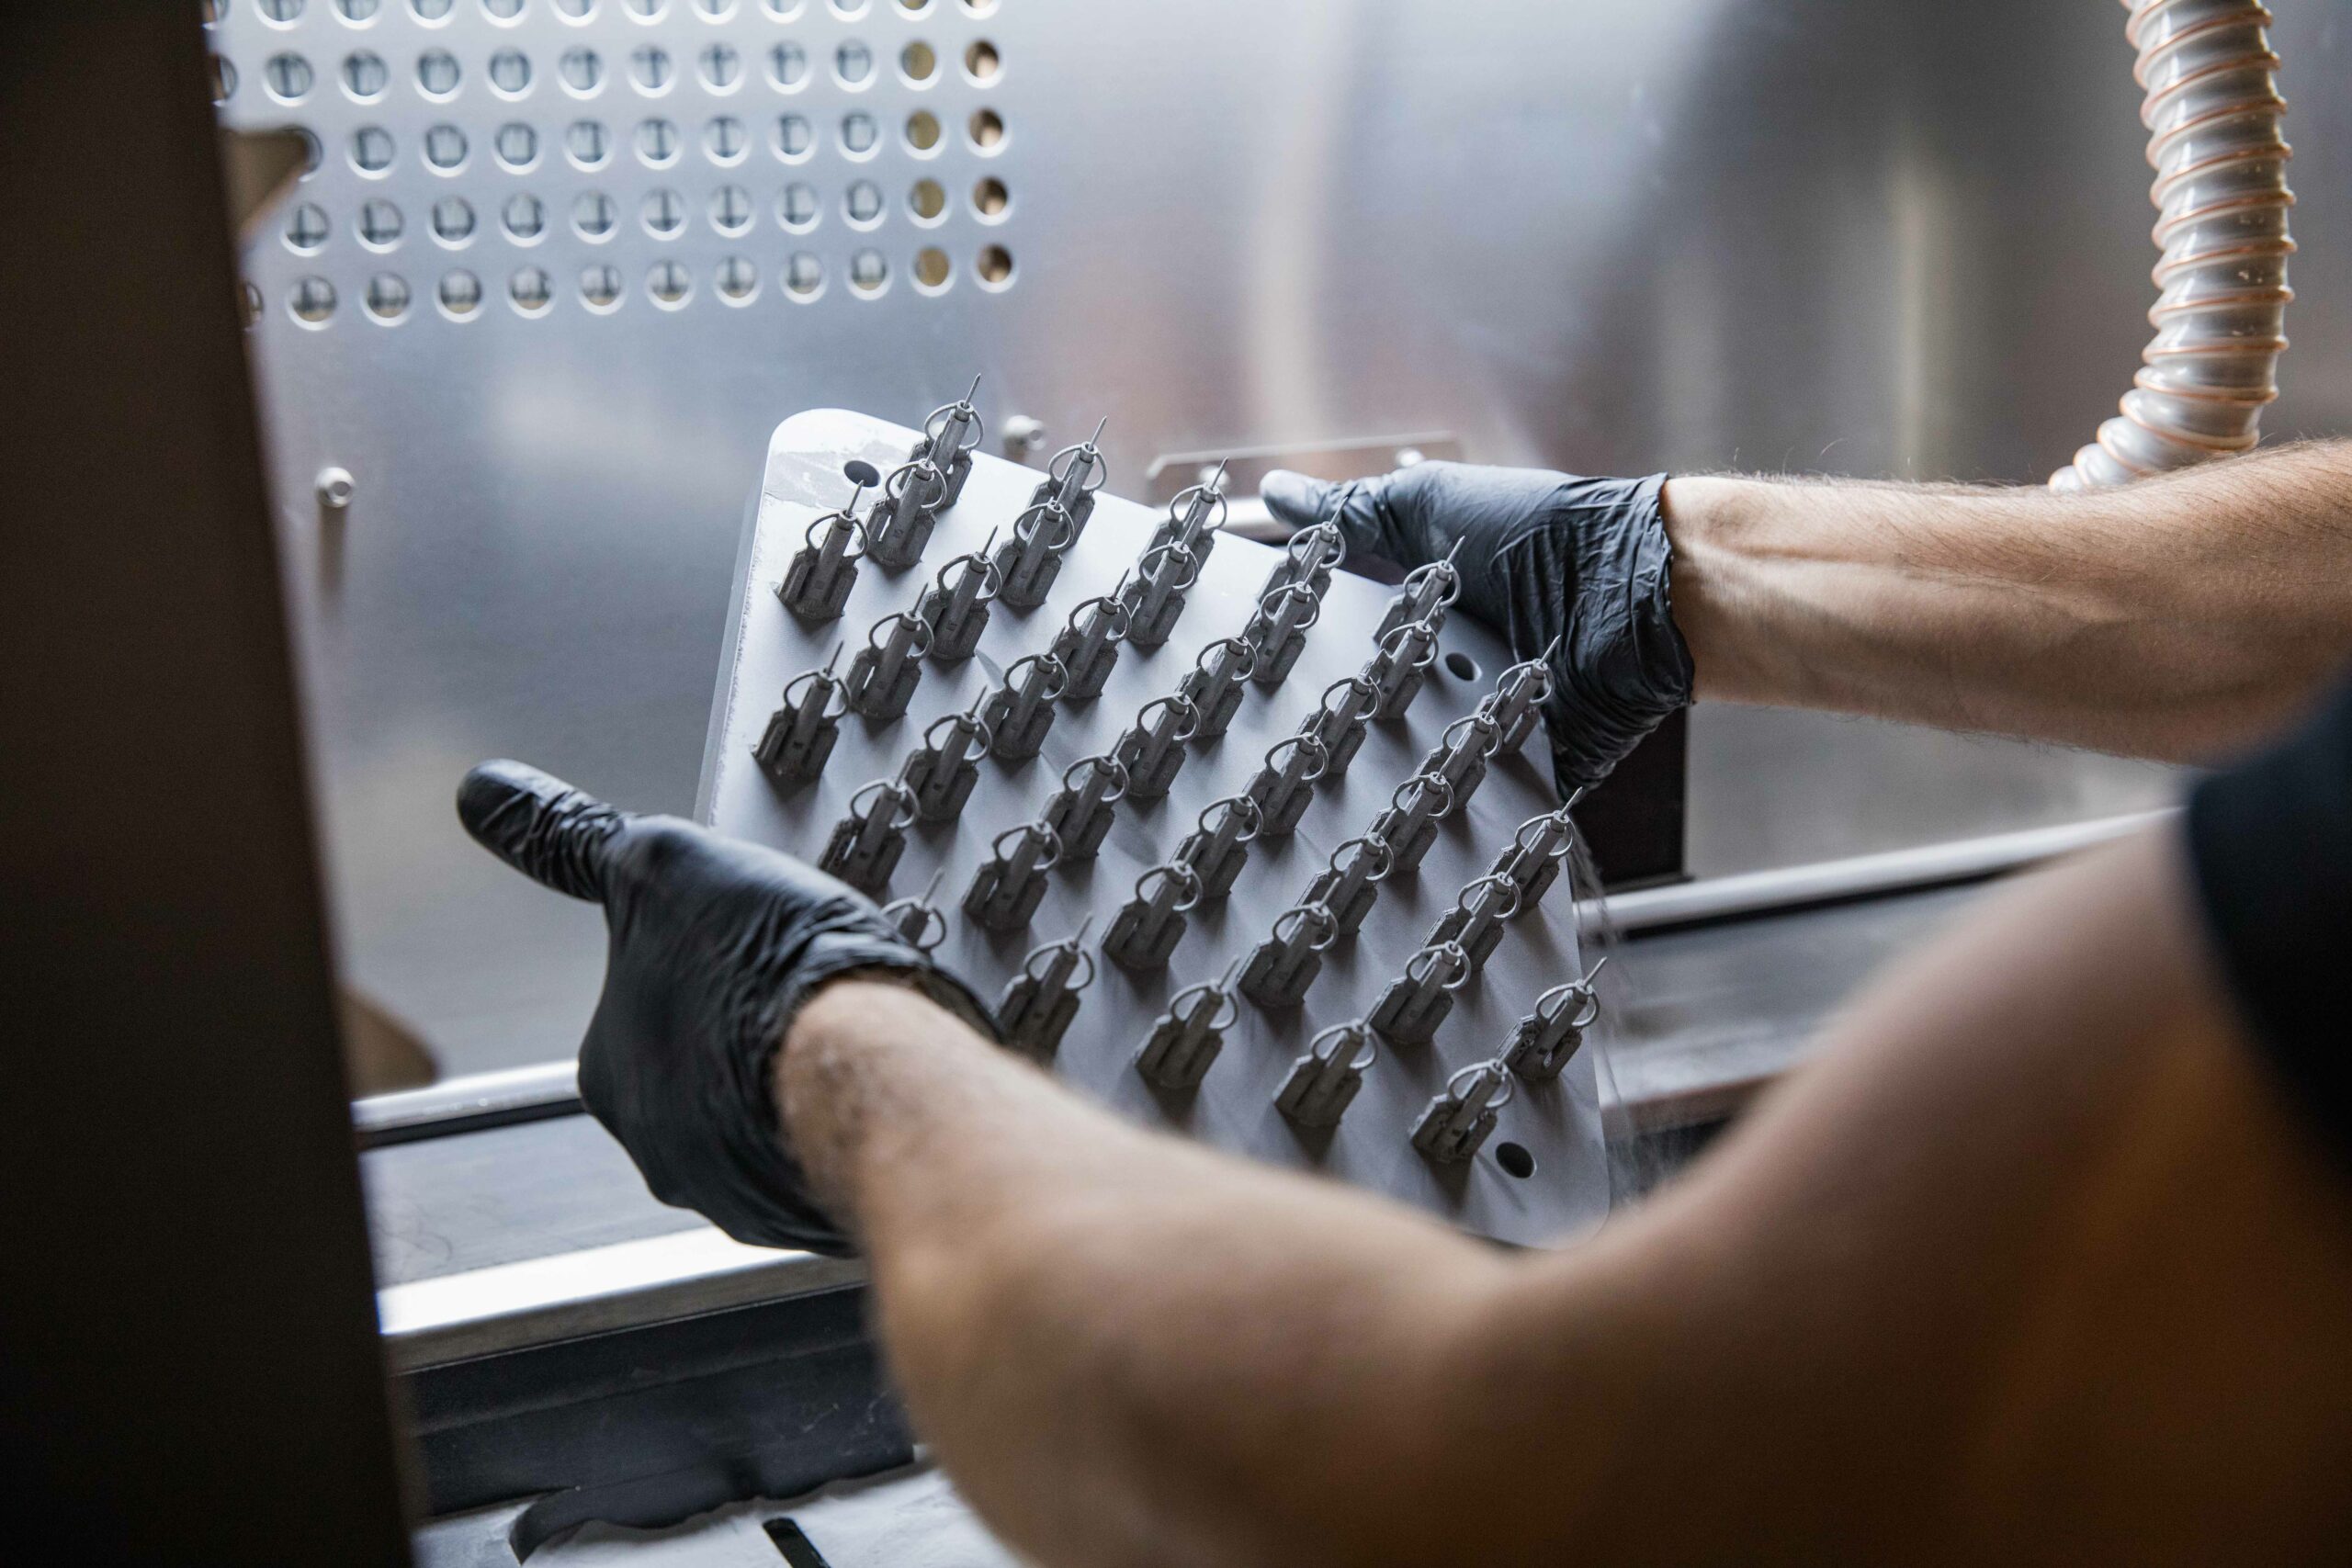
As AM is becoming a key consideration in defense investments, the fact that the White House prioritizes military superiority will play to the strengths of the technology.
COVID-19 confirmed the ability of AM to address supply chain issues. With these measures, Just-In-Time (JIT) manufacturing can truly be deployed, with a strong reliance on micro-factories produced in the US.
China continues to consolidate its position as a major force in the global AM market, with a forecast published by Additive Manufacturing Research in May 2024 projecting $8 billion in Chinese AM market activity by 2032, with U.S. companies still relying heavily on Chinese OEMs across their supply chains. With the tariffs in place, the strategy is clear: scale fast, integrate broadly, and deploy AM technologies both domestically and worldwide.
As far as constraints are concerned, the case of Stratasys highlights the problem of filament sourcing. Beyond that single example lies a structural problem: the infrastructure for a full AM supply chain repatriation is not yet there. Reshoring can truly strengthen AM and U.S. manufacturing if companies bring back the full supply chain. But is it truly doable and profitable? This situation has also generated uncertainty, making it difficult for companies to execute long-term purchasing and investment decisions.
One year later, what’s the status quo?
When customers change, so does the business
For those operating at the production end of the AM ecosystem, the tariff shock arrived through their customers.
At Protolabs, Ryan Kees, Global Product Director for 3D Printing, observed a clear change in order flow. Competitors relying on overseas production networks saw their cost structures disrupted, and customers turned toward domestic suppliers to meet both short-term delivery needs and cost pressures.
He notes: “We have seen an increase in orders on our 3DP business as Protolabs has domestic production capabilities. Many network-model competitors have overseas production partners which incurred increased costs as tariffs were implemented, so customers are turning to domestic suppliers to meet their short term and cost needs.”
Interestingly, this change did not seem to be a huge surprise for Kees as the nature of AM meant that reshoring was less of a leap than in other manufacturing segments. Many customers already had U.S.-based AM suppliers in their supply chain. The transition seemed like a natural step.
At Velo3D, the perspective from the equipment side reinforces this. Michelle Sidwell, Chief Revenue Officer, notes that the company’s domestic manufacturing orientation pre-dates the tariff environment entirely.
She explains: “To date, tariffs have had a limited impact on our business because we’ve intentionally built around domestic manufacturing and sourcing. Supporting a strong U.S. industrial base has always been part of our strategy, not simply a response to changing trade policies.”
What has changed, however, is the nature of the conversation with customers. Sidwell describes how AM is increasingly being evaluated as production infrastructure. “The conversation has shifted from ‘Should we explore additive?’ to ‘How quickly can we scale production?’”
This signals that tariff pressure is functioning, at least in part, as an adoption accelerator, compressing timelines that would otherwise have taken years.
From the OEM side: AM as a supply chain design choice
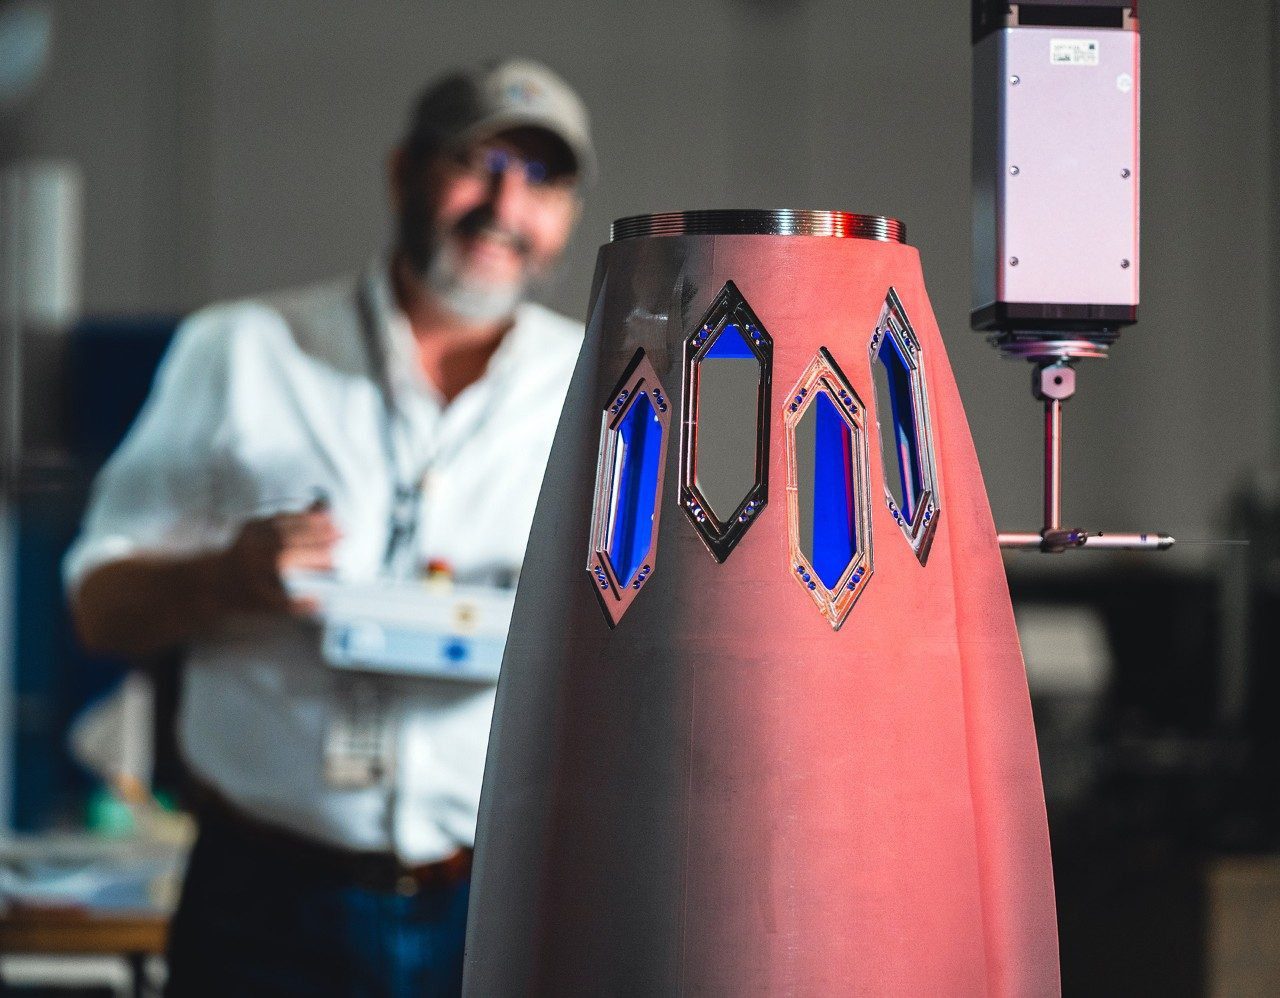
Understanding how demand-side players (the OEMs) are responding brings another key perspective to this new landscape. Lockheed Martin’s approach offers one of the most documented examples of AM being embedded as a supply chain design principle.
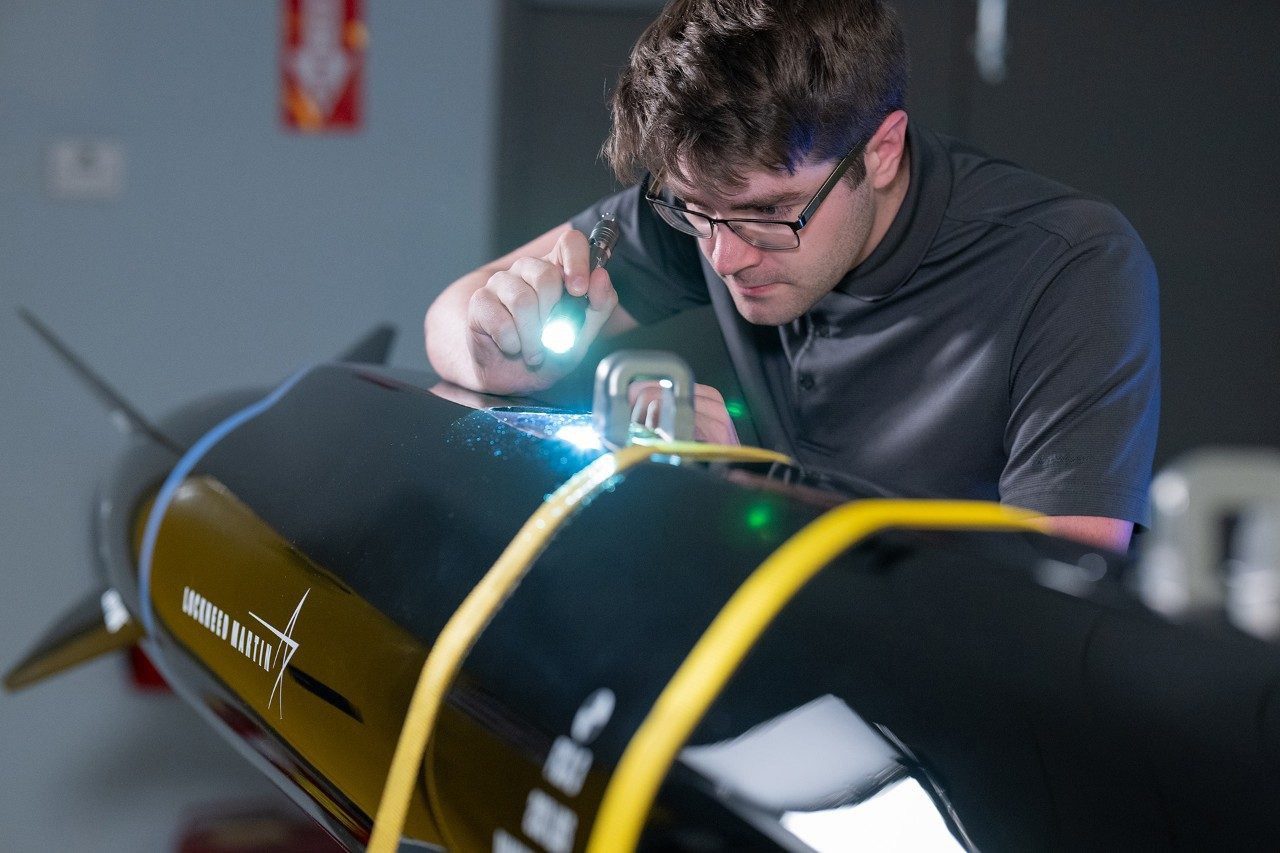
The aerospace and defense prime has been integrating additive manufacturing across its production programs to reduce dependencies on external suppliers, consolidate complex assemblies, and shorten procurement cycles. Its Grand Prairie, Texas facility, expanded in early 2024 to accommodate large-format multi-laser machines.
Tom Carrubba, VP of Production Operations at Lockheed Martin Missiles and Fire Control, has described this commitment in terms of empowering engineers to innovate and rapidly integrate new capabilities to the production floor, creating “affordable and modular designs that can simplify both high and low-volume production processes.” A concrete example concerns the cockpit of the F-35 Full Mission Simulator. For this training device, Lockheed Martin reports that 3D printing can reduce conventional-part lead times by 75% and the number of conventional metal parts by 70%.
These gains represent a structural reconfiguration of how a prime manages its supply base. Interestingly, they were already underway before April 2, 2025. The tariff environment may have accelerated budget justifications and board-level conversations elsewhere, but for OEMs at this level of AM maturity, the direction of travel was already set.
So, what happens further down the supply chain, where the same conviction and investment capacity do not exist?
The resilience test: how deep does it go?
The perspectives from Velo3D and Protolabs highlight a gap between the reshoring narrative and the infrastructure required to support it. Speaking of powder supply in particular, one of the most frequently cited bottlenecks, Velo3D’s Sidwell outlines:
“Powder supply is important, but it’s only one piece of a resilient manufacturing strategy. More importantly, we encourage customers to think beyond a single source of supply. Success isn’t about securing a single powder source; it’s about creating a manufacturing ecosystem that can reliably scale production when and where it’s needed.”
Protolabs’ Kees offers a ground-level account of what supply chain resilience actually requires in practice. Despite not experiencing significant disruption, the company has had to make deliberate adjustments: increasing safety stock, performing targeted pre-buys, and in some cases negotiating customer-specific agreements to secure specialty resin grades with limited sourcing options.
“Our business model as an on-demand manufacturer prevents long-term forecasting of material needs. With that, close customer communication and sales team relationships are critical to anticipate needs and justify pre-buys,” Ryan Kees emphasizes.
This means that being resilient requires constant relationship management, commercial flexibility, and an eye to act on early signals. We can imagine how this practice can be hard to sustain for smaller service bureaus or less capitalized operators.
That said, when asked about the realistic path from reshoring intent to qualified production, Kees acknowledges a spectrum: some customers can transition immediately because their requirements align with existing processes; others require six to nine months of migration work. And that range assumes the customer already knows what they want, which is not always the case.
Looking ahead: what this year has actually revealed
What the past year has confirmed is that AM’s value proposition continuously matures into something more defensible than it was five years ago.
While companies like Velo3D seem to be the best off in this scenario (in particular, due to the fact that domestic manufacturing is their operating model from day one), other companies needed to be more cautious and strategic.
Protolabs, for example, invested in certifications (ISO 13485 for medical, AS9100D for aerospace) that allowed them to absorb demand without scrambling for qualification. We learned that Lockheed Martin had invested in facility infrastructure and digital thread capabilities that made AM operationally deployable.
Tariff pressure has, in several cases, accelerated conversations that were already underway. But it has not resolved the underlying structural gaps: powder supply concentration, the cost and time of qualification cycles, workforce readiness, and a long-standing capacity dilemma. Manufacturers hesitate to invest in new production lines without firm customer commitments, yet customers are reluctant to commit until that capacity is already in place.
For AM businesses navigating what comes next, a few things are worth keeping in mind:
- Identify the certifications and qualifications required for the intended application, market and customer. Requirements must be checked case by case; certification is not universally mandatory for all AM businesses.
- The distributed model is becoming a competitive differentiator. Customers are not always looking to build internal capability. They want access to qualified production without the capital commitment.
- Proximity to the customer is more valuable than proximity to the part. Be careful, we are not talking about geographic footprint here. Understanding what a customer will need six months before they ask for it, and being able to justify a pre-buy on that basis, is a strong advantage.
- The tariff environment will keep shifting. Building strategy around supply chain resilience, domestic capability, and customer trust remains the path forward. The companies that frame their AM investment in those terms will be better positioned regardless of what trade policy looks like in 2027.
*This dossier was first published in the May/June edition of 3D ADEPT Mag. Featured image: 3D ADEPT
THE 3D ADEPT WEEKLY NEWSLETTER
The industry moves fast. Stay ahead.
Every week, the latest additive manufacturing news, in-depth features and real-world applications, straight to your inbox. Plus, be the first to know when a new issue of 3D ADEPT Mag is out.
Free · One email a week · Unsubscribe anytime
Clicking loads our email provider’s sign-up form, including its analytics and Google’s anti-bot protection. You’re only subscribed if you complete the sign-up. Read our privacy policy.